On 2 October 2026, the Queensland Government selected a four-company joint venture as preferred tenderer for PLR2026-1-7, a 305 square kilometre block on the eastern flank of the Taroom Trough. The partners are Xstate Resources, which will act as initial operator, Amplitude Energy, Beetaloo Energy Australia and Eastern States Energy. Each holds an equal 25% working interest, acquired with no upfront consideration.
On the surface it is a modest award. A small block, a competitive tender, no money changing hands. But the composition of that joint venture is more revealing than the acreage itself, and it says something about where the Taroom Trough now sits in the thinking of Australian operators.
None of the four is an established Taroom Trough producer. Two of them have built their businesses in entirely different basins, and one renamed itself fifteen months ago specifically to signal focus somewhere else.
What PLR2026-1-7 Actually Is
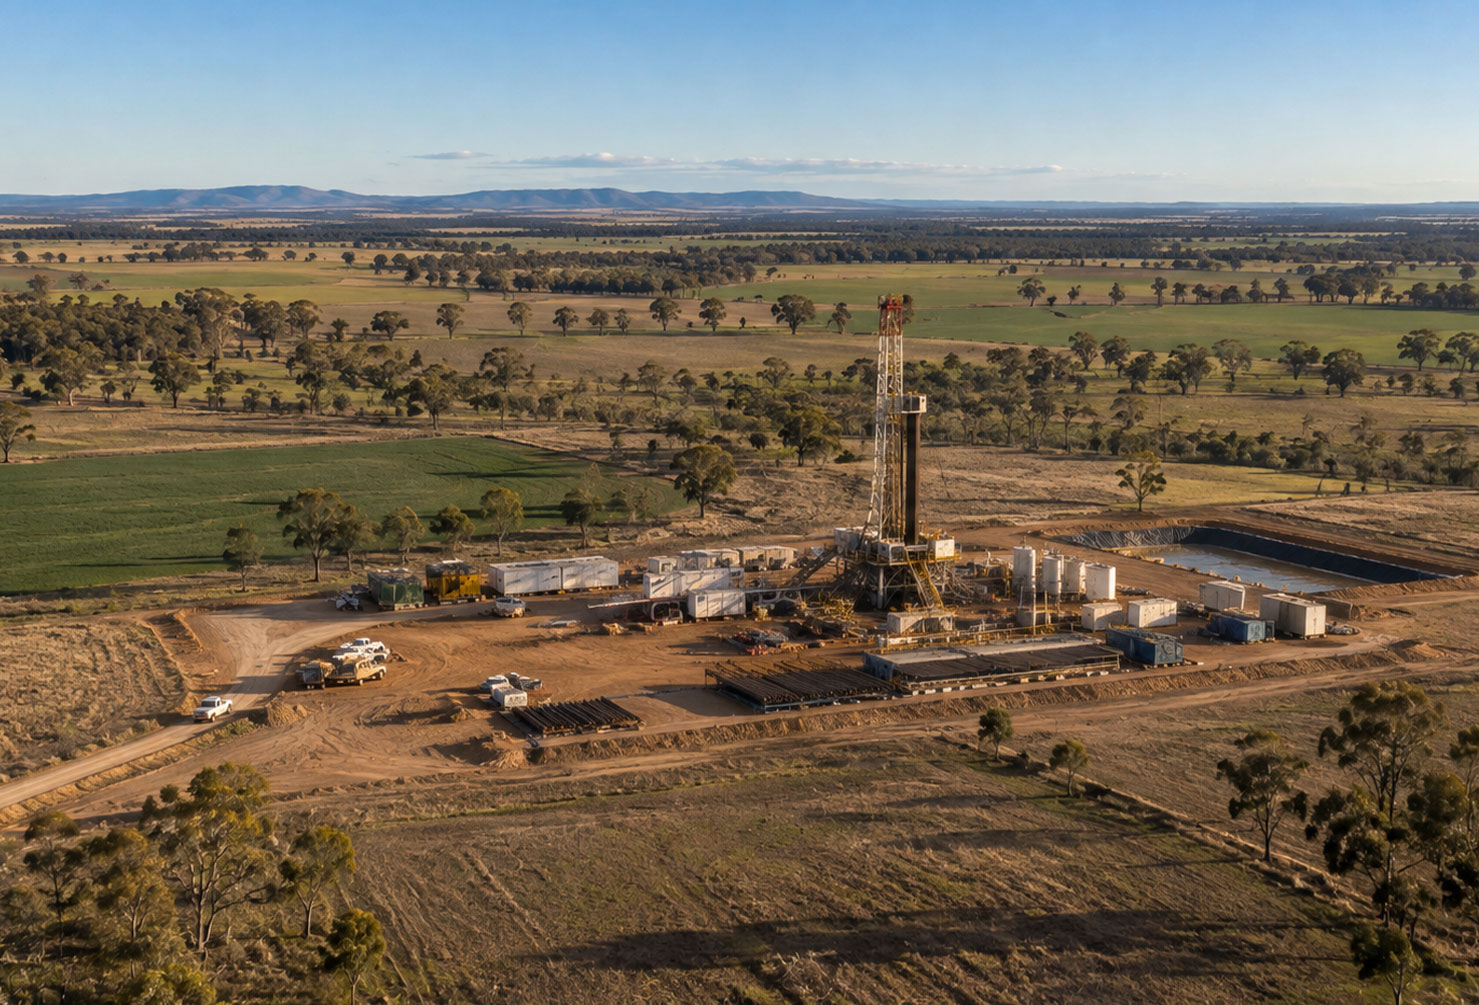
The block covers approximately 305 square kilometres on the eastern flank of the Taroom Trough, between Miles and Condamine in the Western Downs region of southern Queensland. It sits within the broader Bowen and Surat basin system, adjacent to established hydrocarbon provinces with existing pipeline, road and rail infrastructure nearby.
The technical reason the block attracted a competitive tender is its position. PLR2026-1-7 lies adjacent to and along trend with Omega Oil and Gas’ acreage, in broadly the same depth window as the Canyon play where Omega has been running its appraisal campaign. Canyon-3 delivered results that exceeded pre-drill expectations, confirming the Canyon Sandstone extends at least 20 kilometres east to west, and Canyon-4 has followed. Recent drilling in this part of the Taroom Trough has demonstrated encouraging results, and the block’s value rests largely on whether that play extends into it.
Beetaloo Energy has indicated its share of near-term expenditure will be funded from existing cash. No drilling program has been announced, and early work is expected to be seismic-led.
Who the Four Partners Are and What Each Brings
This is where the award becomes interesting, because the four companies are not variations on the same theme.
Xstate Resources takes the role of initial operator, carrying responsibility for the early work program.
Amplitude Energy, formerly Cooper Energy until its rename in November 2024, holds its 25% through wholly owned subsidiary Cooper Energy (VO) Pty Ltd. Amplitude is best known as an offshore operator. It holds the production licence for the Annie gas field targeting first gas in 2028, it recently drilled Juliet-1 in Commonwealth waters as part of its East Coast Supply Project, and its operated Casino, Henry and Netherby assets feed the Athena Gas Plant near Port Campbell. It also holds onshore interests, though they look nothing like this one: a 25% non-operated stake in oil production licences on the western flank of the Cooper Basin in South Australia, operated by Beach Energy, and onshore Otway Basin gas exploration interests in Victoria.
Beetaloo Energy Australia holds its interest through subsidiary Imperial Oil and Gas A Pty Limited. The company was Empire Energy Group until June 2025, when shareholders approved a rename and the ASX code moved from EEG to BTL. Managing Director Alex Underwood described the change at the time as reflecting a strategic focus on the Beetaloo Sub-basin. The company holds 28.9 million acres of exploration tenements across the McArthur Basin and Beetaloo Sub-basins in the Northern Territory and is advancing its Carpentaria project toward production. Its contribution here is unconventional resource development expertise, and its interest is non-operated.
Eastern States Energy is the private partner in the group.
What the four have in common is that none of them is an incumbent Taroom Trough operator. They have pooled capital and capability to take a position in a basin that, eighteen months ago, almost nobody outside Shell, Elixir, Omega and Santos was seriously pursuing.
Why This Entry Is Different From the Others
This is the third Taroom Trough land release story in roughly a month, and the pattern across the three is worth comparing.
In mid-September the Queensland Government awarded 1,138 square kilometres on the eastern flank to a joint venture of Omega Oil and Gas, Tri-Star and Beach Energy. That award expanded the position of an operator already drilling in the basin, with an established ASX-listed producer joining it.
A week later came further awards: more than 1,000 square kilometres to a Denison Gas and OGT Energy joint venture on the western flank, adjoining OGT’s existing processing and pipeline infrastructure, and a further 411 square kilometres to Shell QGC, which described the acreage as a domestic market and backfill opportunity.
Those were incumbents and adjacent operators consolidating. PLR2026-1-7 is different. It is four companies, none of them established in the basin, splitting a block evenly at no upfront cost to find out whether the play extends. That is a lower-conviction, lower-cost entry than the earlier awards, and it tells you the basin has moved past the point where only specialists are paying attention.
It also tells you something about how Queensland is running the process. Three separate tender outcomes in a month, across both flanks, to a mix of incumbents, adjacent infrastructure owners, a supermajor subsidiary and now a four-way consortium of outsiders. The Queensland Government has been explicit that opening new acreage is about building the project pipeline, and the spread of successful tenderers suggests the approach is working.
What This Means for the Workforce
A 305 square kilometre block with a seismic-led early work program does not generate immediate employment at any scale. The workforce significance of this award is cumulative rather than direct.
Across roughly four weeks, the Taroom Trough has added Beach Energy, Tri-Star, Denison Gas, OGT Energy, additional Shell QGC acreage, Xstate Resources, Amplitude Energy, Beetaloo Energy and Eastern States Energy to a basin that already had Shell, Elixir, Omega and Santos active. That is a substantial expansion in the number of organisations that will be commissioning seismic, evaluating data, planning wells and eventually drilling in the same geography over the same period.
The near-term demand is in the evaluation disciplines. Seismic acquisition and processing specialists, geophysicists and interpreters, geologists with Permian experience in the Bowen and Surat system, and the commercial and regulatory professionals who handle tenure, landholder access and work program compliance in Queensland. Those roles are needed before a single well is drilled.
The medium-term demand follows the same path the incumbents are already on. Drilling engineers with deep onshore unconventional experience, wellsite geologists and petrophysicists, completions engineers with multi-stage stimulation experience in tight Permian sandstone. That pool is already stretched by the active programs Shell, Elixir and Omega are running, and every new entrant adds a claim on it.
The Transferability Question
The composition of this joint venture raises a question worth taking seriously, because it applies well beyond one block.
Both Amplitude and Beetaloo Energy bring genuine capability. Neither brings capability built in this basin, in this play type, under this regulatory framework.
Amplitude’s onshore experience is real but it is conventional and it is interstate. Non-operated oil production licences on the Cooper Basin western flank in South Australia, and gas exploration interests onshore Otway in Victoria. The Taroom Trough is unconventional tight Permian sandstone requiring multi-stage hydraulic fracture stimulation, under Queensland tenure, with Queensland landholder access arrangements. Its strongest operational capability, offshore subsea and platform operations under Commonwealth regulation, has limited application to an onshore Queensland seismic and drilling program.
Beetaloo Energy’s unconventional credentials are genuine, but they were earned in the Beetaloo Sub-basin: a different rock type, a different jurisdiction and a different operating environment. The company renamed itself in June 2025 specifically to signal focus on that basin. Taking Queensland acreage fifteen months later is a departure from that positioning, and the expertise does not port across as cleanly as the word unconventional suggests.
This is the point that gets glossed over in acreage announcements. Expertise in unconventional development is not a single transferable skill set. Stimulation design, completion strategy, landholder engagement and regulatory navigation are all basin-specific to a degree that operators tend to understate when entering new ground.
What both companies have done about it is sensible. Each has taken a non-operated minority position with Xstate carrying operational responsibility. That structure buys exposure and understanding without requiring capability they do not yet have. If the play proves up and either wants a larger role, the capability question stops being theoretical.
What to Watch
Preferred tenderer status is not a granted permit. The award is a step in the Queensland land release process and the work program commitments attached to it will determine what actually happens on the ground and when.
The more important variable is Omega. PLR2026-1-7 is valuable largely because of its position along trend from the Canyon play. Canyon-4 results are expected to follow Canyon-3, and Omega has further appraisal wells planned. If those results continue to confirm the extent and quality of the Canyon Sandstone, blocks adjacent to and along trend from it become considerably more attractive. If they disappoint, a four-way consortium holding a 305 square kilometre block with a seismic-led work program has lost very little.
That asymmetry is precisely why the structure makes sense. Four partners, equal shares, no upfront cost, exposure to a play that is being de-risked by somebody else’s drill bit. It is a reasonable way to take a position in a basin that is attracting serious attention but has not yet proven commercial development at scale.
For the Australian upstream workforce, the signal is simpler. The Taroom Trough now has more operators, more acreage under tenure and more capital committed than at any point in its history, and the people who can evaluate, drill and complete wells in Permian tight reservoirs are going to be busy in Queensland for some time.