On 28 September 2026, Finder Energy announced that Timor-Leste’s Autoridade Nacional do Petróleo had approved the Environmental Impact Statement for the Kuda Tasi and Jahal development. Together with the Field Development Plan approved in July, it puts the principal regulatory foundations in place as the project moves toward a final investment decision.
The announcement will not register widely in Australian energy coverage. A three-well oil development with 22.2 million barrels of proved and probable reserves is small by the standards of the projects that usually attract attention. But KTJ carries a significance that has nothing to do with its size, and for anyone thinking about workforce in the Asia-Pacific region it is one of the more interesting things happening right now.
It is set to become the first offshore oil development taken through development approval entirely under Timor-Leste’s own sovereign petroleum regime. And it arrives at a very specific moment in the country’s industrial history.
What KTJ Actually Is
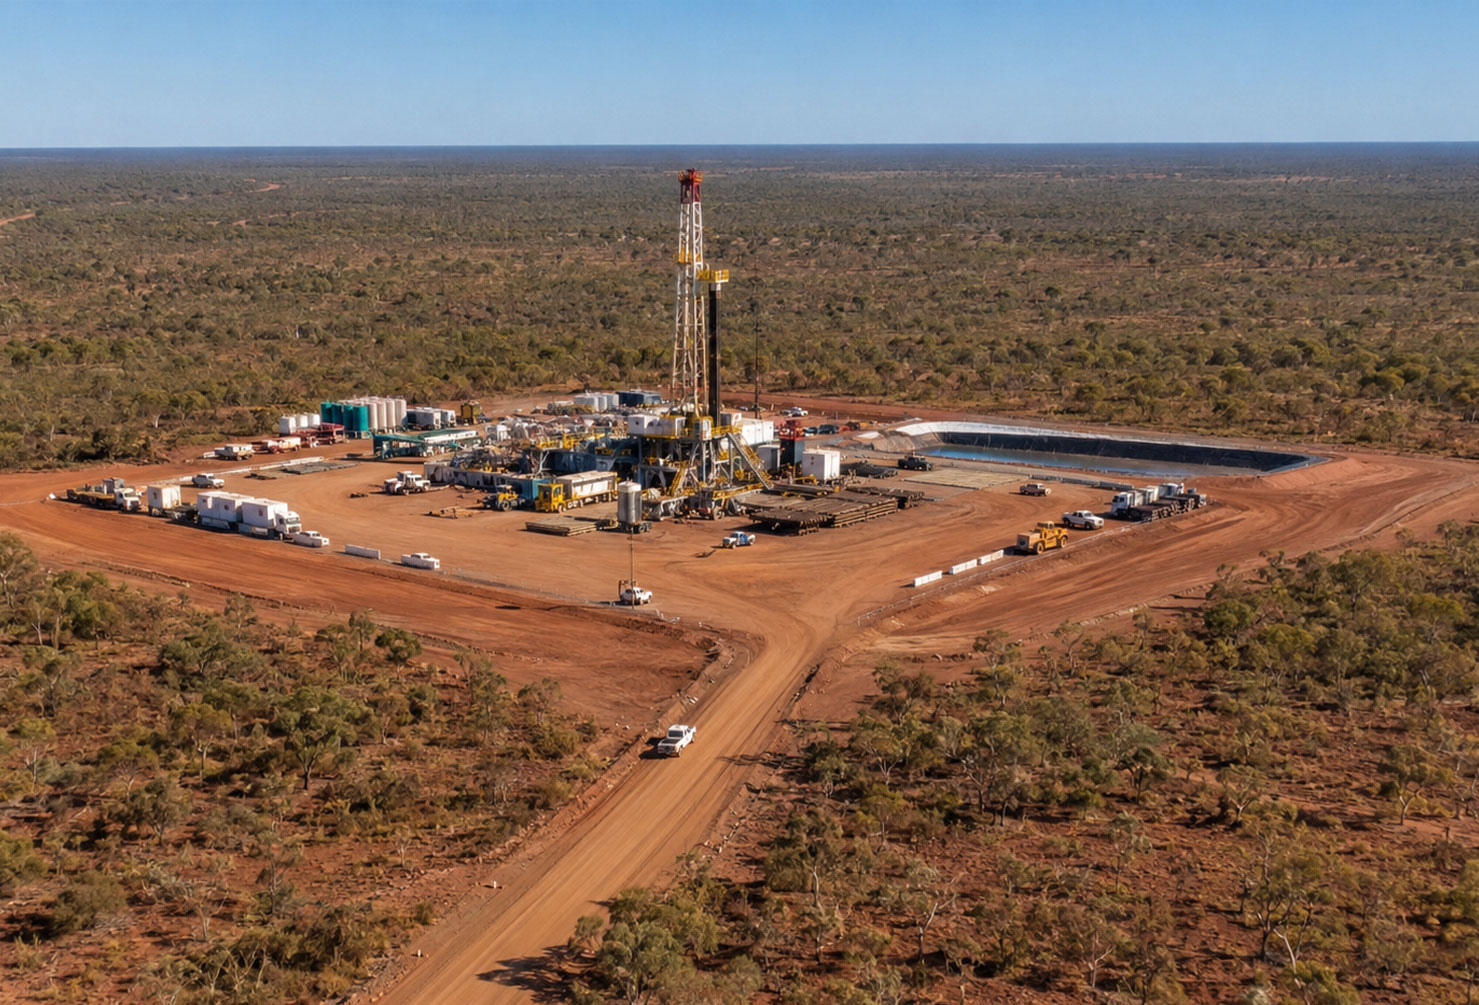
The Kuda Tasi and Jahal fields sit in the Timor Sea within PSC 19-11, in the Laminaria High oil province offshore Timor-Leste. Finder Energy holds 66% and operates. TIMOR GAP, the national oil company of Timor-Leste, holds the remaining 34%.
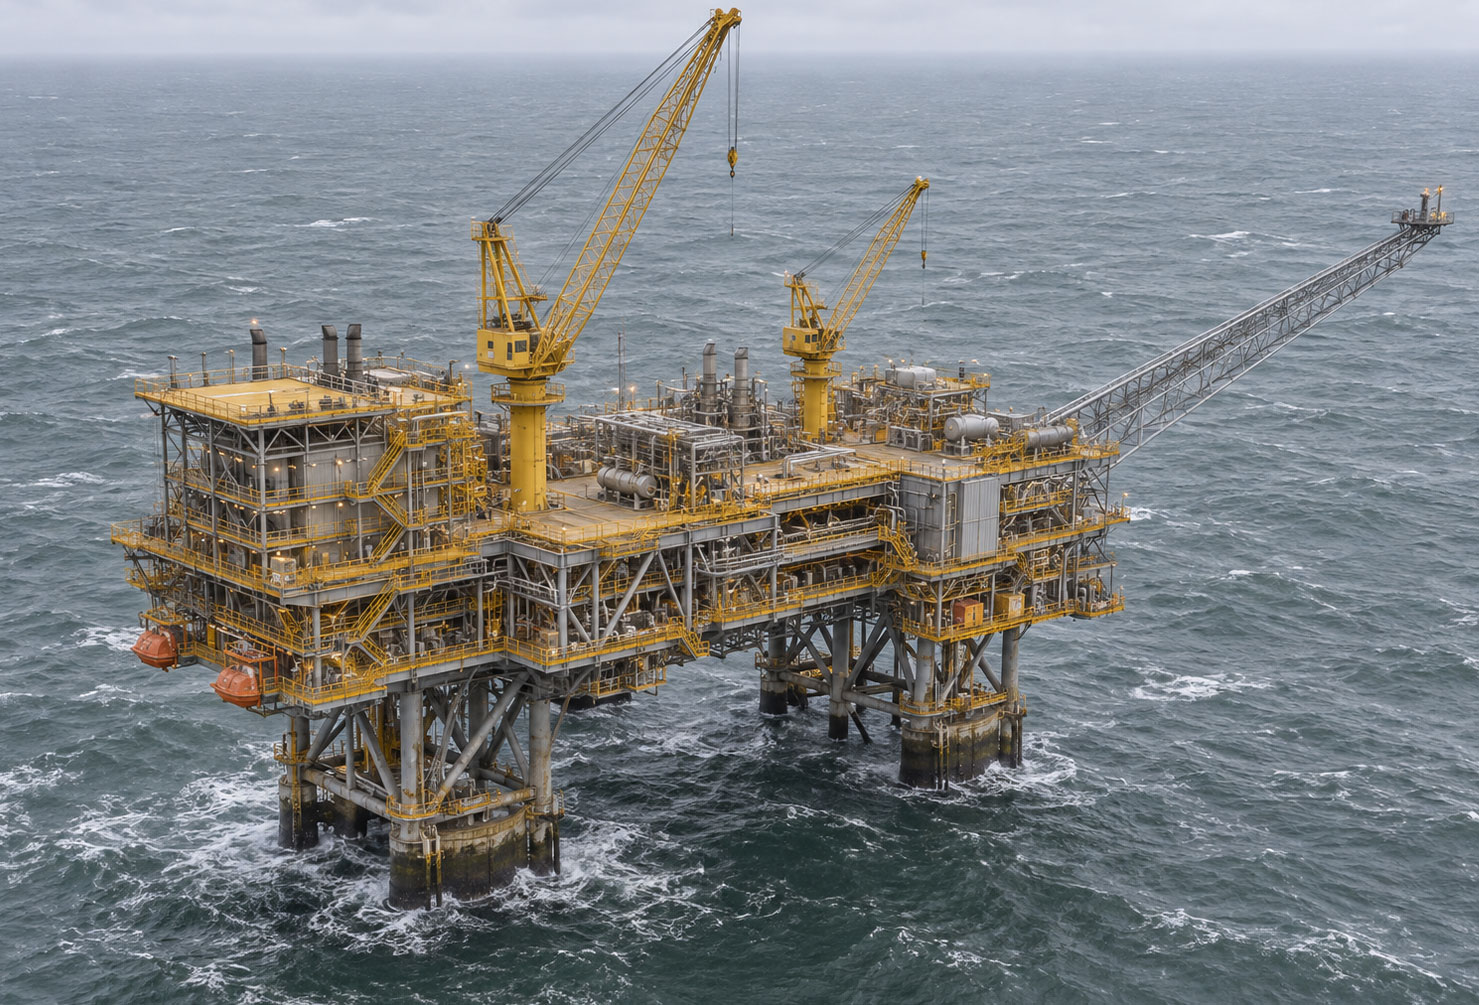
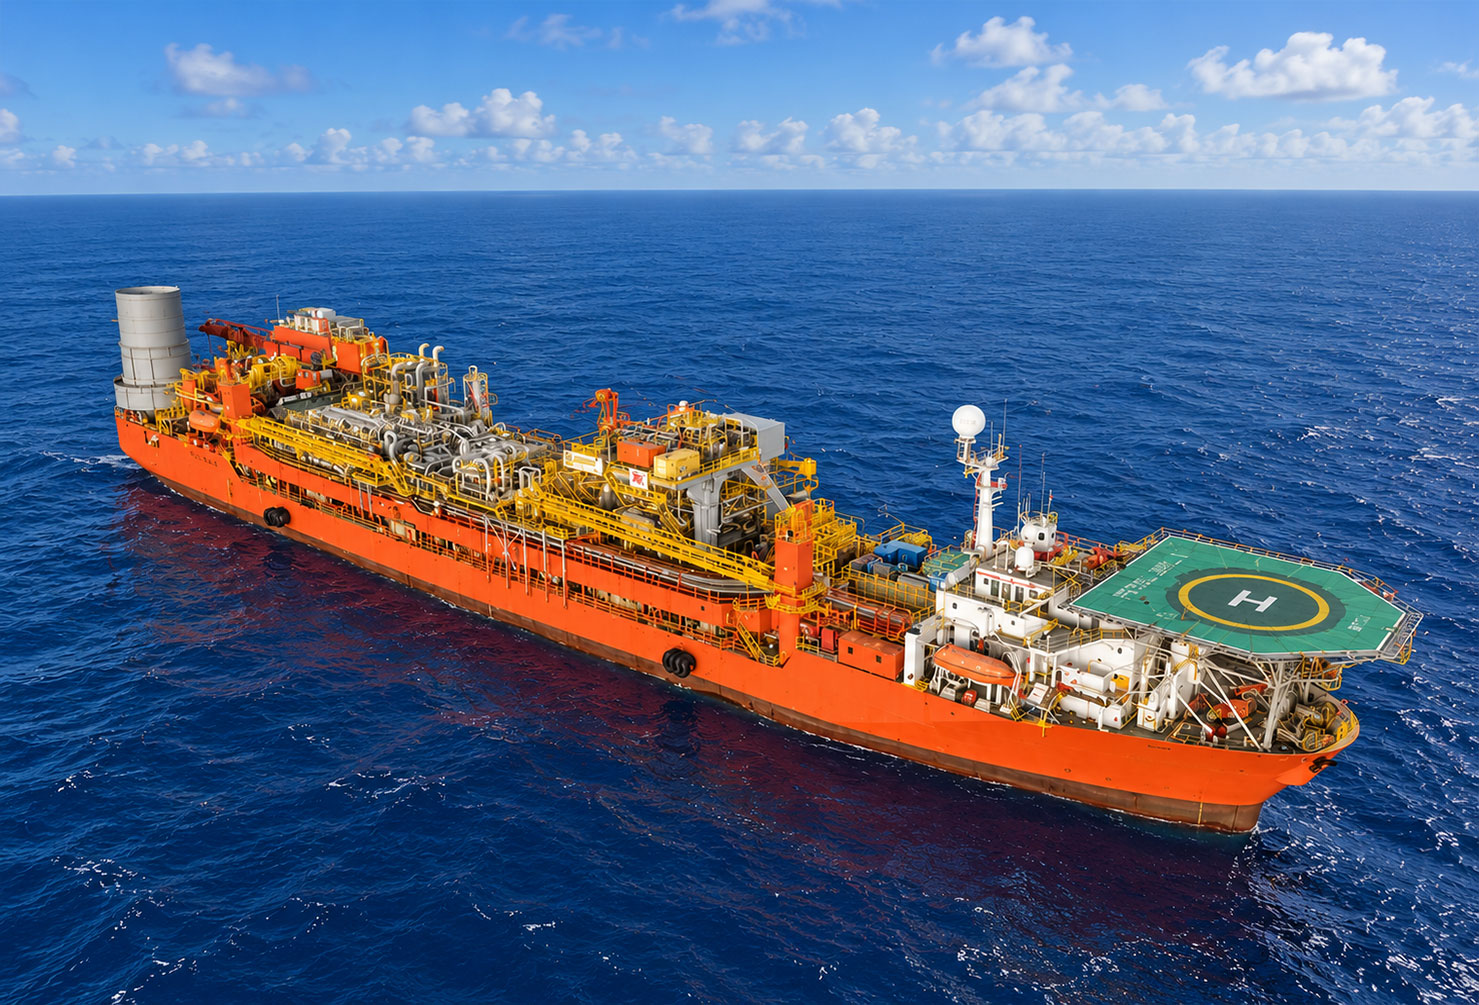
The first development phase involves three subsea production wells, two at Kuda Tasi and one at Jahal, tied back to a floating production storage and offloading vessel. The joint venture has confirmed a maiden reserves classification of 22.2 million stock tank barrels for that initial phase. A potential fourth infill well at Kuda Tasi would add gross best estimate contingent resources of 2.2 million barrels, taking the combined total to 24.4 million barrels. RISC Advisory supported the technical work behind the development plan.
Production is facility-constrained at 25,000 to 30,000 barrels per day, with the operator indicating roughly 14 to 15 million barrels recoverable in the first two years. First oil is targeted for late 2027 to early 2028.
The facilities have been deliberately sized beyond what the first phase requires. Reprocessed Ikan 3D seismic over the nearby Krill and Squilla discoveries is being interpreted to support evaluation of second phase developments that would tie back into the same infrastructure. The design intent is a development that can absorb further discoveries across PSC 19-11 rather than one sized only for the fields currently sanctioned.
Why the Sovereign Regime Point Matters
Timor-Leste has produced petroleum before. Bayu-Undan supplied gas to Darwin LNG from 2006 and produced from 2004 until it ceased permanently on 4 June 2025, delivering 34 wells across three development phases and funding the sovereign wealth fund that continues to underpin the state budget.
But Bayu-Undan was developed under the Joint Petroleum Development Area arrangement shared with Australia. It only came under full Timor-Leste jurisdiction in August 2019, when the Maritime Boundaries Treaty entered into force and the former JPDA transitioned to ANP supervision. By that point the field was well into the back half of its life.
KTJ is different in kind. It has been permitted, assessed and approved by Timor-Leste’s own regulator, under Timor-Leste’s own petroleum framework, with the national oil company as a joint venture partner rather than a late entrant. A Development Area was approved over the project in the first quarter of 2026, with tenure of up to 25 years attaching on approval of the Field Development Plan in July. That is a country’s petroleum regime working end to end.
The EIS itself reflects that. It was prepared by specialist environmental consultancy MCC Sustainable Futures in partnership with Timor-Leste advisory group Halona Serena, and developed through consultation with regulators, local communities and the broader public, including a town hall meeting held in Dili on 2 June 2026.
The Workforce Timing Is the Real Story
This is where KTJ becomes genuinely interesting from a workforce perspective, and it is a matter of timing more than anything else.
At the end of its life, Bayu-Undan supported around 350 onshore and offshore jobs in Timor-Leste, with more than half of the offshore workforce Timorese and the operator’s entire Timor-Leste workforce made up of local employees. Over two decades, that project built something the country did not previously have: a population of people with direct, hands-on offshore oil and gas operational experience in the Timor Sea.
Production ceased in June 2025 and the decommissioning agreement, signed in November 2023, is now in effect. Decommissioning work sustains employment for a period, but it is finite by definition and the skills it demands are not identical to those required to run a producing asset.
KTJ targets first oil in late 2027 or early 2028. That is close enough to the end of Bayu-Undan production that the operational capability built there has not yet dispersed, and far enough away that the intervening period has to be managed deliberately rather than assumed. Countries that lose an experienced offshore workforce to other markets during a gap between projects rarely get it back quickly.
For operators and contractors working in the region, that creates a specific and time-limited opportunity. There is a body of people with Timor Sea offshore experience, local language and local knowledge, who are between assets. Identifying and engaging them ahead of the KTJ construction and operations phases is materially easier now than it will be in eighteen months.
Local Content Is a Requirement, Not a Preference
Anyone planning workforce for a Timor-Leste development needs to understand that local content obligations are formal and structured rather than aspirational.
TIMOR GAP states plainly that a local content plan is a key requirement under its agreements, contracts and negotiations with joint venture and business partners, with an early focus on training nationals so that the required skills are available. Regulator representatives have publicly described the local content framework as organised around training and employment, provision of goods and services, knowledge transfer, and formal local content commitments recorded in contract annexes.
TIMOR GAP has also built operational service capability of its own, through drilling and services and marine seismic subsidiaries that have worked on real campaigns including the Bayu-Undan infill well program and an Eni drilling campaign. These are not shell entities.
The practical implication for workforce planning is that a KTJ contractor cannot simply mobilise an entirely international crew and treat local content as a reporting exercise. The structure expects genuine employment, genuine training and genuine knowledge transfer. Organisations that plan for that from the outset execute more smoothly than those that discover the requirement during contract negotiation.
The FPSO Ownership Model Changes the Picture
One feature of KTJ is unusual enough to be worth drawing out, because it has direct workforce consequences.
In December 2025, Finder and its wholly owned subsidiary Jarl Marine acquired the Petrojarl I FPSO from Amplus Energy for approximately US$15 million under a sale and purchase agreement and a share subscription agreement. The vessel has a processing capacity of 30,000 barrels per day and will be redeployed to the KTJ field.
Most FPSO developments of this size lease the vessel from a specialist owner who supplies the marine and production crew as part of the package. Eni’s Kitan development in the former JPDA, which produced from 2011, used exactly that model with a leased FPSO under third party operation. Owning the asset outright lowers operating cost and gives the operator more control over schedule, which is why Finder has pursued it.
Ownership also shifts responsibility. Finder has contracted Amplus Energy, the vessel’s previous owner, to handle integration, life-extension work and production-phase operations, so day-to-day FPSO operation is still contracted. But as owner, Finder carries the asset’s integrity, class and flag obligations, and it has more direct say over how the vessel is crewed and how local content is built into that workforce. For a company moving from explorer to producer, that is a meaningful step up, and it begins well before first oil.
What Still Has to Happen
The regulatory foundations are in place. The commercial ones are not yet complete.
Finder had targeted FID within the September 2026 quarter, having previously indicated mid-2026. On 5 October the company confirmed that the FID deadline under its farm-in agreement with TIMOR GAP has been extended from 30 September to 30 November 2026, with all other terms unchanged, including TIMOR GAP’s commitment to fund 50% of development capex up to a US$338 million cap. Finder has said debt financing is in its final stages, subject to final terms and required approvals, with Barrenjoey engaged to arrange it. The drilling rig contract is progressing through final approvals with execution targeted for October, and EPCI contracts are nearing close.
Long-lead procurement commenced earlier in 2026 with TIMOR GAP support, specifically to protect the first oil schedule against slippage in the FID date. No change to the first oil target was disclosed alongside the extension, which suggests the operator still expects the late 2027 to early 2028 window to hold.
It is worth being straightforward about the risk. A small-cap operator taking FID on its first development, in a jurisdiction with a young regulatory framework, dependent on debt financing that is not yet closed, is not a certainty. The regulatory milestones achieved this year are real and they de-risk the project substantially. They do not eliminate execution risk.
Why This Is Worth Watching From Australia
KTJ is a Timor-Leste project, but the operator is Perth-based, the technical work has been led from Australia, and the engineering, subsea and project management capability being applied is drawn from the same Asia-Pacific pool that Australian projects compete for.
It also sits in a part of the region where activity has been thin for some time. Bayu-Undan has stopped. Greater Sunrise remains unresolved. The status of Chuditch is uncertain following an ANP termination notice issued over the PSC that contains it. KTJ proceeding to FID would be the first new offshore oil development in Timor-Leste waters since Eni’s Kitan field, and the first under the sovereign regime, with facilities designed to host tie-backs from Krill, Squilla and any further discoveries across PSC 19-11.
For workers with FPSO, subsea or Timor Sea operational experience, and for organisations that support offshore development in the region, a project reaching FID in this location is not a routine event. It is the difference between a petroleum province with a future and one that is winding down.