Offshore decommissioning gets written about as a bill. A liability on a balance sheet, an obligation attached to an asset, a problem to be deferred and provisioned for. When it appears in the trade press it is usually in the context of who has to pay for it and when.
For the people who work in the sector, that framing is close to backwards. Decommissioning is some of the longest-duration, most predictable and most heavily regulated work available in Australian energy right now. It is already underway, it has named contractors on multi-year scopes, and it is one of the few parts of the industry with a workload that is visible more than a decade ahead.
Almost nobody talks about it as somewhere to build a career. That is a gap worth closing.
The scale is not speculative
In November 2025 the Department of Industry, Science and Resources published a liability estimate prepared by Xodus Group. It estimates industry will spend A$43.6 billion decommissioning Australia’s offshore oil and gas infrastructure in Commonwealth waters to 2070, rising to A$66.8 billion once inflation is factored in.
That was lower than the previous estimate of A$61.8 billion, a reduction the study attributed to better forecasting assumptions and a more mature understanding of well decommissioning, pipeline removal and vessel mobilisation. Cost estimates will keep moving. The physical inventory behind them is the part that matters for anyone planning a workforce, and it is specific: more than 700 wells, around 7,600 kilometres of pipelines, 520 subsea structures, and at least 2.7 million tonnes of infrastructure to be removed.
Two facts about that inventory matter more than the dollar figure.
The first is timing. Around 55% of the work falls before 2040. This is not a problem for the next generation to inherit. It sits inside the working life of almost everyone currently in the industry.
The second is geography. The liability concentrates where the offshore workforce already lives: 61% of it sits off Western Australia, 23% off Victoria and 16% off the Northern Territory.
It is not a future industry. It is a current one.
The clearest evidence that decommissioning has moved from planning to execution is that you can name the contracts.
Woodside, as operator of the Gippsland Basin Joint Venture, in which it and Esso Australia Resources each hold 50%, reported in its third quarter results that it had completed decommissioning of three Julimar-Brunello exploration wells, plugged and abandoned five wells across Julimar-Brunello and the North West Shelf, continued conductor recovery activities at the Cobia field, completed preparatory work for the Snapper campaign, commenced the Barracouta A plug and abandonment campaign, and progressed execution readiness for the Echo Yodel pipeline removal.
That is six distinct scopes of decommissioning work, at different stages, inside a single quarter, at one operator.
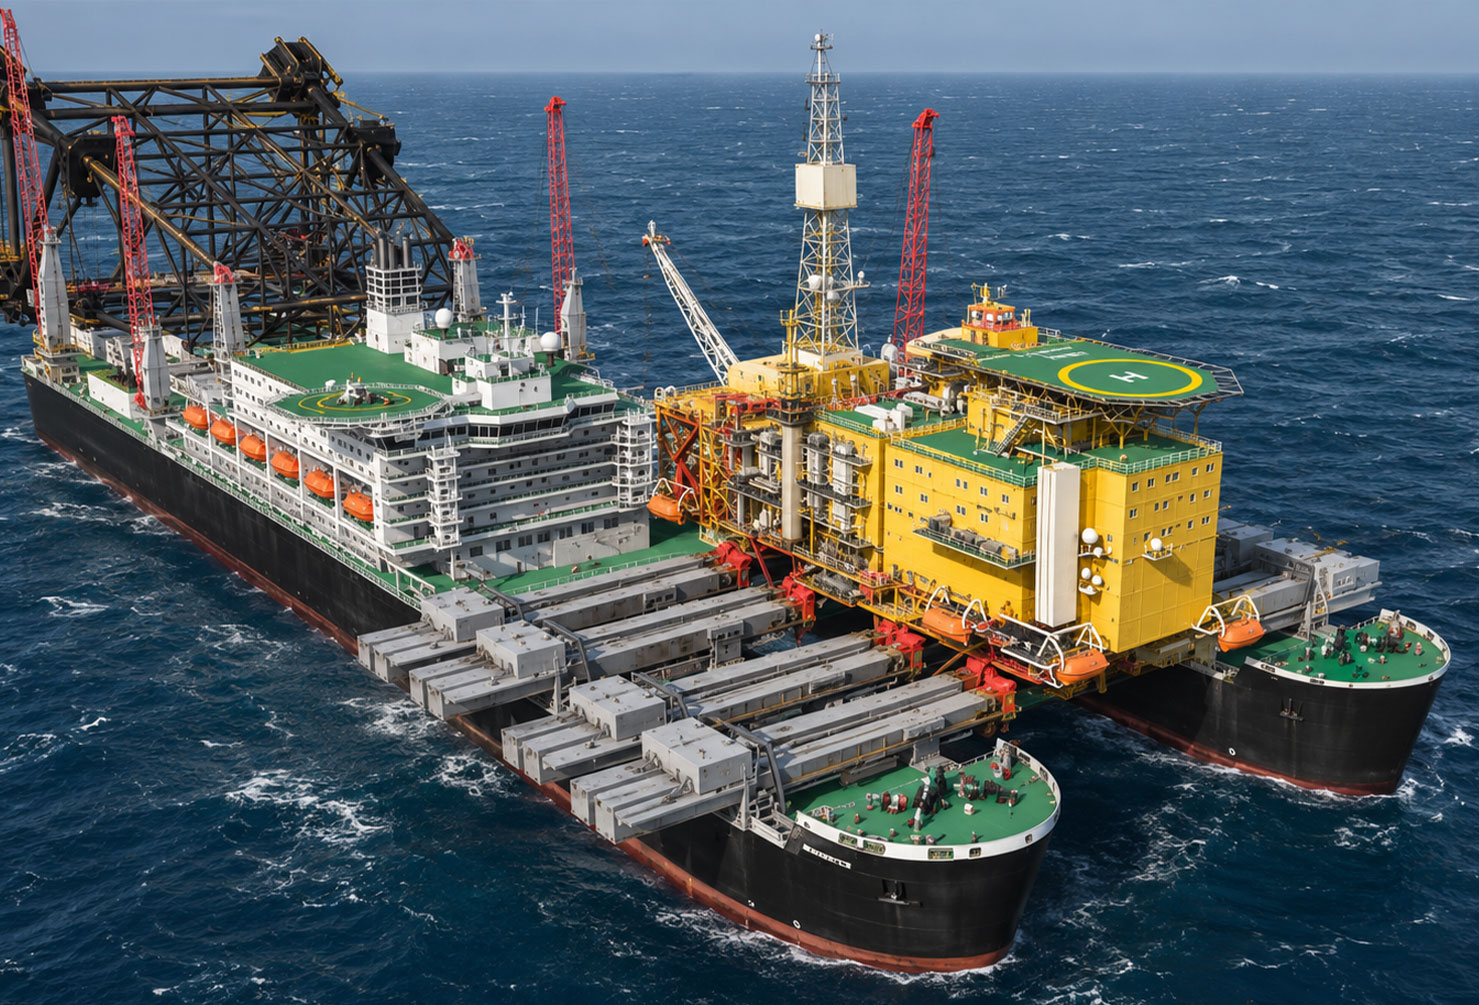
The Northern Endeavour programme, covering the Laminaria-Corallina fields about 550 kilometres north west of Darwin, is the one most people have heard of and the one that shows the structure of this work most clearly. It is being run in phases by the Commonwealth. Phase 1 has covered suspending the wells, flushing the subsea pipelines and disconnecting the Northern Endeavour FPSO from the fields it had served since 1999. Phase 2 is the permanent plugging and abandonment of nine subsea wells. Phase 3 is removal of the remaining subsea infrastructure.
In August the Australian government awarded Zenith Energy Australia the lead contract for Phase 2 following an international tender. Separately, Xodus and Elemental Consulting Services are supporting environmental approvals and regulatory activities across Phases 2 and 3.
Northern Endeavour is also the reason Australian decommissioning law looks the way it does. The field’s operator collapsed, the obligation landed with the Commonwealth, and the government has been running and funding the clean-up ever since. That single failure reshaped the rules for everyone else, which is the subject of the next section.
And the support contracts run just as long. OEG holds a multi-year extension to supply around 200 DNV 2.7-1 certified offshore cargo carrying units from its facility at Barry Beach in Victoria, along with inspection, maintenance and repair services and crane and lifting support, to a global operator in Bass Strait, running through the expected end of field life in 2036.
What the work actually consists of
The most useful thing about a programme like Northern Endeavour is that the published contract scopes tell you precisely what the jobs are.
Zenith’s Phase 2 scope covers project management and engineering, detailed well engineering, execution planning, regulatory approvals, management of the offshore plug and abandonment operations, transport and storage of recovered infrastructure and materials, and field monitoring through to handover to Phase 3.
The environmental and regulatory scope sitting alongside it covers environmental impact assessment, support for approvals under the EPBC Act, oil spill modelling, GIS work, regulatory engagement and implementation planning.
Read those two lists together and the shape of the discipline becomes obvious. A single decommissioning programme calls on well engineering, subsea and marine operations, heavy lift and logistics, waste handling and materials recovery, environmental science, regulatory and approvals specialists, and the project controls function that holds it all together. These are not adjacent skills borrowed from construction. They are a distinct capability set, and on a programme of any size they are needed concurrently rather than in sequence.
Why it behaves differently from construction work
Australian offshore careers have largely been shaped by construction cycles. A project is sanctioned, demand spikes, people move, the project finishes and demand collapses. Anyone who worked through the last decade knows the pattern.
Decommissioning does not behave that way, for three reasons.
- The work is obligatory, and the obligation follows you. A company can defer a development indefinitely if the economics turn. Decommissioning is a condition of having produced the field. After the Northern Endeavour, Australia went further: amendments to the Offshore Petroleum and Greenhouse Gas Storage Act passed in August 2021, with the expanded provisions taking effect in March 2022, allow the regulator to direct former titleholders and related parties to carry out remedial work. The primary obligation still sits with the current titleholder and the government describes the call-back power as a last resort, but the direction of the law is not ambiguous.
- The pipeline is visible. Decommissioning scope is driven by asset age and cessation of production, both of which are known years ahead. Nobody has to guess whether the work will exist.
- The duration is long. A contract running to end of field life in 2036 is a different proposition from an eighteen-month construction engagement, and it changes what a career built around this work can look like.
That combination, obligatory work on a visible pipeline over long durations, is unusual in this industry. It is the closest thing to a structurally stable workload that Australian offshore energy currently offers.
The honest caveats
None of this makes decommissioning easy work or a guaranteed path.
It moves slowly and it is approvals-heavy. Zenith’s engineering and planning on Northern Endeavour Phase 2 is proceeding, but execution of the offshore campaign remains subject to Commonwealth approval. That is normal for this kind of programme and it means schedules can and do shift for reasons that have nothing to do with the engineering.
It is also not glamorous. There is no first gas, no ribbon to cut and no production record to point at. The measure of a successful decommissioning campaign is that nothing happened, which is a harder thing to build a reputation on.
And the commercial model is still settling. Ownership changes complicate it further. When XRG agreed in November to buy Shell’s 16.67% non-operated interest in the North West Shelf, it agreed to assume the decommissioning obligations attached to that interest, with completion expected in 2027 subject to regulatory approvals. Liabilities of this kind now move with equity, and that changes who is planning the work and on what timeline.
What this means if you are planning a workforce
The capability needed to run a decommissioning campaign well is not currently abundant in Australia, and it is not the same capability that delivered the construction boom.
The specific scarcity sits in well engineering for abandonment, subsea removal planning, and the regulatory and environmental approvals work that governs both. These are the roles that determine whether a campaign is scoped realistically, and they are needed during planning rather than during execution, which is exactly when organisations are least inclined to resource them properly.
The operators who will do this well are the ones treating decommissioning as a programme with its own capability plan, rather than as a tail-end activity that the operations team absorbs alongside everything else.
What this means if you are planning a career
If you have worked on late-life assets, well abandonment, subsea removal, marine operations or offshore environmental approvals, you have experience in a market that is growing while much of the rest of the sector contracts. That is worth being deliberate about rather than treating it as what you happened to end up doing.
If you are coming from construction or commissioning, much of the underlying technical skill transfers. What does not transfer automatically is the regulatory literacy. Decommissioning is governed by approvals in a way that construction is not, and the people who are valuable in this market are the ones who understand both the engineering and the consent regime it operates under.
And if you are early in your career, this is one of the few parts of Australian offshore energy where you can look at a published programme, see the phases laid out, and know roughly what work will exist in ten years. That is rare, and it is worth more than it currently gets credit for.
The short version
Australia is going to spend decades and tens of billions of dollars taking its offshore infrastructure apart. That work is already being tendered, awarded and executed, by named contractors on contracts that run into the 2030s.
The industry files it under cost. For the people who do it, it is one of the most durable sources of skilled work in the country. The sooner that is treated as a career path rather than an obligation, the better served everyone will be, including the operators who need these people and have not yet worked out where they are going to come from.